The Basic Principles Of What Does Comprehensive Auto Insurance Cover
His copays extend to physical therapy check outs, where he'll pay $20 for each session. Leon's determined to get whatever back on track so he and Leah can go back to doing the important things they love: spending quality time together outdoors. By discovering how premiums, deductibles, coinsurance and copays work, you can much better understand your health care expenses.
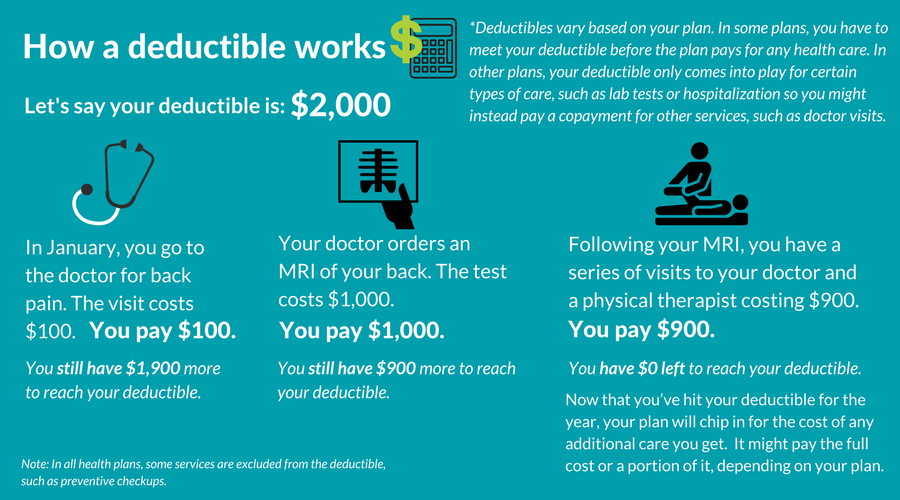
Simply put, a deductible is the amount of cash that you need to pay by yourself behalf before your strategy will start and start to cover eligible medical expenses. The primary advantage of a deductible is that you will save cash on your premium. So the bigger the deductible, the higher the discount rate on your premium.
Other ways to conserve on your premiums include co-insurance, which is another alternative readily available on our MyHEALTH strategies in Asia. The simplest method to illustrate how deductibles work would be through some simple examples. If individual A has a deductible of $500 and required treatment equating to $4,000, then their insurance coverage would cover $3,500 after person A fulfilled their deductible.
What Is Group Term Life Insurance Fundamentals Explained
Person B has a deductible of $2,000 and needs treatment equating to $1,000. Nevertheless, later that year they require another treatment costing $5,000. In this case, person B would cover the $,1000 for the very first treatment and $1,000 of the 2nd, while the insurance would cover $4,000 of the second claim.
So it's constantly essential to inspect both the schedule of benefits and the terms and conditions of the strategy to make certain you totally understand how deductibles and any other premium conserving system work prior to you buy. Below are some methods deductibles might differ across plans. Sometimes, they might use to your plan as a whole, but in other cases deductibles only apply to particular benefits.
Usually, medical insurance deductibles are applied on a per term basis, or per duration of insurance coverage. This suggests that once you have actually fulfilled your deductible, all eligible expenses during the rest of that duration of insurance coverage will be covered, but that your deductible will reset at the beginning of the next duration of insurance coverage, assuming you have renewed your policy.
Get This Report on How Much Does Long Term Care Insurance Cost
Oftentimes, people get our MyHEALTH prepares as a way to top up or the protection supplied by an existing medical insurance policy they might have through their work or their spouse. This is to help cover qualified medical costs that the existing health plan would not have covered.
Not just will it help decrease your premium, however you can apply qualified expenses covered by your existing insurance coverage policy towards the deductible on your MyHEALTH strategy, even if it is completely covered by the existing policy. Many health insurance plans will offer a range of deductibles to match various individuals's financial and protection needs.
For example, our MyHEALTH plans offer global coverage, but are customized for people residing in different countries to better suit their everyday health care requirements. how much does home insurance cost. Therefore, different plans provide various deductible levels based upon the local insurance coverage market and healthcare system. MyHEALTH Hong Kong MyHEALTH Singapore MyHEALTH Thailand MyHEALTH Vietnam MyHEALTH Philippines NilUSD 1,500 USD 5,000 USD 10,000 NilSGD 2,000 SGD 5,00010,000 NilTHB 16,375 THB 32,750 THB 81,875 THB 163,750 THB 327,500 NilUSD 500USD 1,000 USD 2,500 how to cancel bluegreen timeshare USD 5,000 USD 10,000 NilUSD 500USD 1,000 USD 2,500 USD 5,000 USD 10,000 Searching for comprehensive worldwide health insurance protection in Asia? APRIL International offers a variety of strategies that offer worldwide protection to people residing in Asia, supplying flexible protection to expats and local nationals alike.
How To Get Therapy Without Insurance for Dummies
We likewise offer group medical insurance strategies for companies of every size, from SMEs to large multinationals. You can click the links listed below for additional information on your alternatives.
Getting medical treatment can be pricey because, wellhealth insurance. Those bills can skyrocket in a brief amount of time if you need healthcare, depending on what your insurance coverage will and will not cover. However what about medical insurance deductibles? How precisely do they work? And how can you make them work much better for you and your family? We'll direct you through the world of health insurance deductibles, explain the various types, and describe what makes one of the most sense when it pertains to deductibles and health insurance.
A medical insurance deductible is the amount you're responsible for paying prior to your medical insurance company starts to share a few of the cost of medical treatment with you. Medical insurance, like any other kind of insurance, includes a monthly or yearly premium the quantity you routinely pay to be insured in the first place.
Some Known Details About What Is A Whole Life Insurance Policy
And that deductible is in impact for the whole year up until it's time to renew or register again. You define your deductible quantity when you register in your medical insurance plan during the registration duration. Let's pretend you have a health insurance strategy with a $1,000 deductible. If you have an accident or develop a disease and need medical treatment, you'll have to pay for the very first $1,000 in medical expenses.
It's great to bear in mind that with the majority of insurance plans, you're able to receive certain regular and preventative health care services (like screenings or immunizations) as standardregardless of whether or not you've met your deductible. is the term used to explain how your medical treatment is paid after you've reached your deductible quantity.
Just how much do I pay in coinsurance? It's a percentage amount depending upon your insurance plan. If you've met your deductible and your coinsurance obligation is 30%, that suggests your medical insurance supplier will pay 70% of each future bill until you fulfill your out-of-pocket optimum for the year.2 See more below.
Some Known Details About How Many Americans Don't Have Health Insurance
It's a fixed amount decided by your specific medical insurance plan. Copays are different than deductibles and coinsurance since you pay a copay whether or not you have actually met your deductible. A copay for a basic journey to your medical professional can be different than a copay for specialized services like physiotherapy, for instance.
An out-of-pocket maximum is the maximum amount your health insurance strategy says you have to pay forcovered health services throughout the year. This figure originates from your deductible, your coinsurance duty and your copays. If you reach this out-of-pocket maximum, then your insurance coverage business pays 100% of your remaining covered medical costs for that year.
Deductibles can can be found in various types depending on the kind of insurance plan you have! Here are the various kinds of health insurance coverage deductibles: Comprehensive deductibleA extensive deductible is a deductible quantity that applies to and consists of all of the medical protections in your medical insurance plan. When you have actually met this extensive deductible, your plan's coinsurance will take effect.
How Much Is Urgent Care Without Insurance for Beginners
Your plan might supply some health services without you having to consume into your deductible. Woo-hoo! Once again, examine to see if the protections without a deductible are advantageous to you. Individual or household deductibles: Your member of the family might have individual deductibles, or the strategy Helpful resources might just have one family deductible. Remember, thanks to the Affordable Care Act, specific preventive care is 100% covered by all non-grandfathered health plans. You do not need to pay any deductible, copay, or coinsurance for covered preventive healthcare services you obtain from an in-network company. Once you meet your out-of-pocket optimum for the year (including your deductible, coinsurance, and copayments), your insurer https://diigo.com/0k1n94 pays 100% of your remaining medically-necessary, in-network costs, presuming you continue to follow the health plans guidelines regarding prior permissions and recommendations.
Your out-of-pocket costs for health care services that aren't a covered advantage of your medical insurance won't be credited towards your health insurance coverage deductible. For instance, if your medical insurance doesn't cover cosmetic treatments for facial wrinkles, the cash you pay of your own pocket for these treatments won't count towards your medical insurance deductible.
There are exceptions to this rule, such as emergency care or situations where there is no in-network provider capable of supplying the needed service. Federal rules need insurance companies to count the expense of out-of-network emergency situation care towards the client's routine in-network cost-sharing requirements (deductible and out-of-pocket optimum) and prohibit the insurer from enforcing greater cost-sharing for these services.
Some Ideas on How Much Is Adderall Without Insurance You Should Know
( That's presuming the state law uses to the person's medical insurance; self-insured plans are not regulated at the state level, and they account for the majority of employer-sponsored coverage.) Health plans that allow out-of-network care, typically PPOs and POS strategies, might differ regarding how they credit money you spent for out-of-network care.
In this case, cash spent for out-of-network care gets credited toward the out-of-network deductible, however doesn't count toward the in-network deductible unless it's an emergency scenario. One caveat: if your out-of-network company charges more than the traditional amount for the service you got, your health plan might restrict the amount it credits towards your out-of-network deductible to the traditional amount.
Copayments typically do not count towards the deductible. If your health plan has a $20 copay for a primary care workplace check out, the $20 that you pay will most likely not count towards your deductible. Nevertheless, it will count towards your optimum out-of-pocket on practically all plans (some grandmothered and grandfathered plans can have various rules in regards to how their maximum out-of-pocket limits work).
An Unbiased View of What Is The Best Medicare Supplement Insurance Plan?
In reality, premiums aren't credited towards any kind of cost-sharing. Premiums are the expense of buying the insurance. They're the price you pay the insurance provider for assuming part of the financial threat of your possible health care expenses. You have to pay the premium monthly, no matter whether you need health services that month or not.

For a growing number of Americans, high deductible health plans are a truth of life. The pattern began a decade back and shows no signs of disappearing. At numerous firms, it's the sole medical insurance that's used for staff members. The assumption is that if employees have to shell out more cash when seeing a physician or filling a prescription, they will have "skin in the video game" so they'll use their healthcare advantages more selectively and avoid wasteful or unneeded procedures and drugs.
Field who is also a speaker at Wharton. Wharton healthcare management teacher David Asch gives the example of going out to dinner on your own penny versus a cost account. You'll naturally be more prudent, states Asch, who is likewise executive director of Penn Medication's Center for Healthcare Innovation.
What Happens If I Don't Have Health Insurance - An Overview
Furthermore, high-deductible strategies increase companies' bottom line by shifting more costs to the employee. The Internal Revenue Service currently specifies a high-deductible health plan as one with a deductible of a minimum of $1,350 for a private or $2,700 for a family, according to health care. gov. Field keeps in mind that many deductibles remain in the variety of $5,000 to $6,000.
On the positive side, people's month-to-month premiums are generally lower. The plans have gained popularity amongst organization owners. In 2014, 41% of consumers with employer-provided coverage had specific deductibles higher than $1,000, up from 22% in 2009, according to the Quarterly Journal of Economics. Moreover, the share of companies using only high-deductible coverage increased noticeably from simply 7% in 2012 to 24% in 2016.
Field includes, "People truly resent those plans where they feel that it appears like insurance, but it actually isn't due to the fact that you have to set up so much of your own money." Some significant business have actually started to backpedal, including JPMorgan Chase and CVS, according to a post last year in the Insurance coverage Journal.
How Long Can You Stay On Parents Insurance Can Be Fun For Everyone
CVS, which had switched all of its workers to high-deductible strategies, realised that some employees had actually stopped filling vital prescriptions and was apparently re-evaluating its policies. "You would not want me to utilize a costly brand-name drug for my heartburn when I might use a much more economical generic [On the other hand,] you don't desire me to stop taking my insulin.
And some are examining whether their use might assist decrease America's breakneck medical spending. "With health care costs increasing faster than [the U.S.] GDP, reducing the growth rate is a primary health policy goal," write Leonard Davis Institute associate fellow Molly Frean and Wharton health care management teacher Mark Pauly in a recent National Bureau of Economic Research study working paper, "Does High Cost-Sharing Slow the Long-lasting Growth Rate of Health Spending? Proof from the States." They, too, keep in mind the extensive usage of high-deductible health insurance: in 2018 the percentage of workers with a basic annual deductibles reached 85%, and their average deductible was $1,573 for private protection.
Gupta, Field, and Asch all believe that the concept of high-deductible health insurance may hold promise for reducing total expenses, however not considerably, at least in their current form. "I think it's one tool, however overall it's not going to be a game-changer," Field states. Gupta agrees, adding that while research study on these plans has actually revealed that people do cut back on care, "the decrease isn't really large it's [just] on the order of 5% to 10%." The share of employers using just high-deductible coverage increased significantly from simply 7% in 2012 to 24% in 2016.
What Is A Premium In Health Insurance Things To Know Before You Get This
Another issue with high-deductible strategies is whether they really lead people to make great decisions about when they require a doctor and when they don't. Asch states this is a significant problem: Many people simply do not have the medical know-how to compare high-value and low-value care. "You would not want me to use a pricey brand-name drug for my heartburn when I could utilize a much less expensive generic," he says.
However high-deductible health insurance do not discriminate between those 2 buying decisions." They rely on the patient to make the call, he says, and while some people can do that successfully, numerous can not. To make things much more complicated, he states, the costly drugs are the ones that get promoted straight to consumers, spurring demand for them.